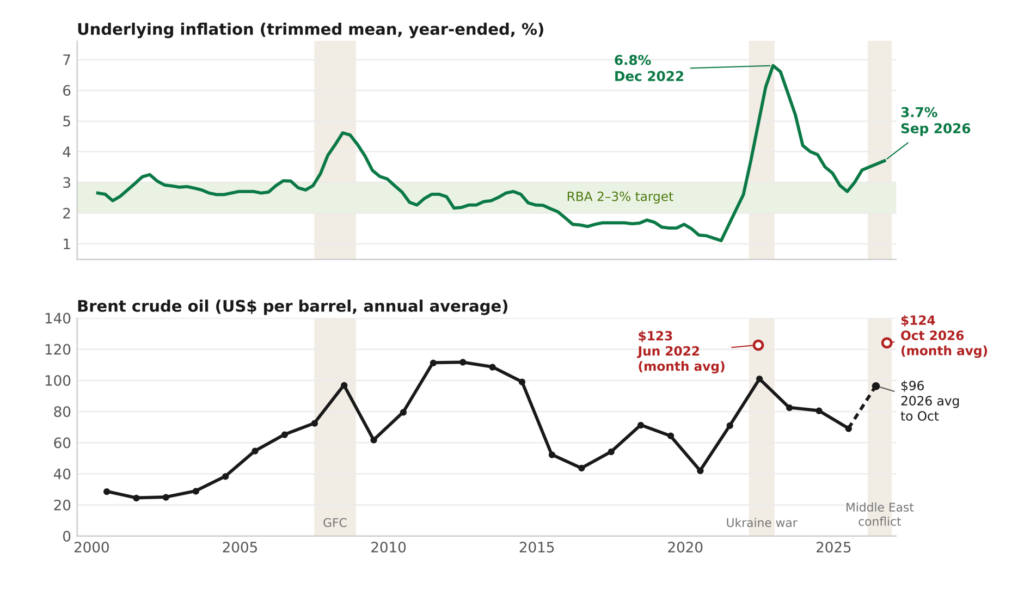
I joined ausbiz to discuss inflation, where we are in the credit cycle, and where I see the opportunity.
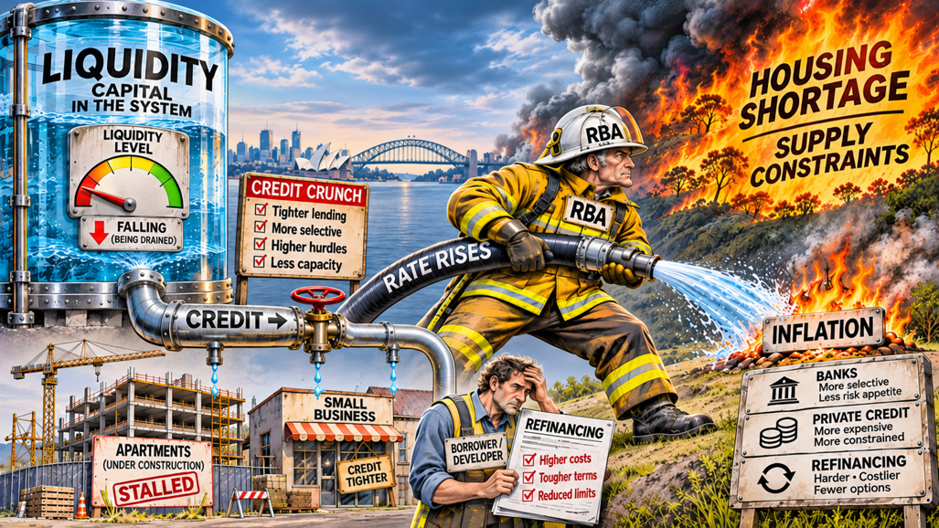
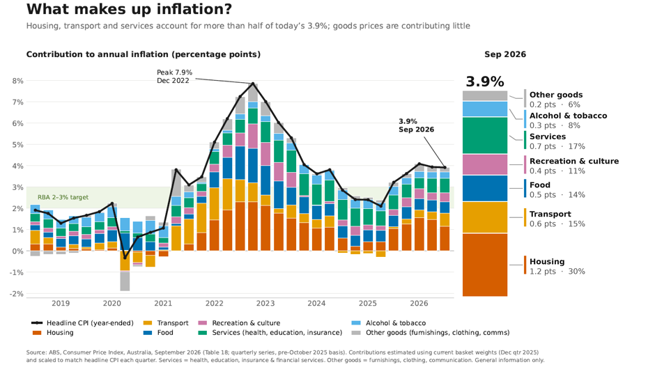
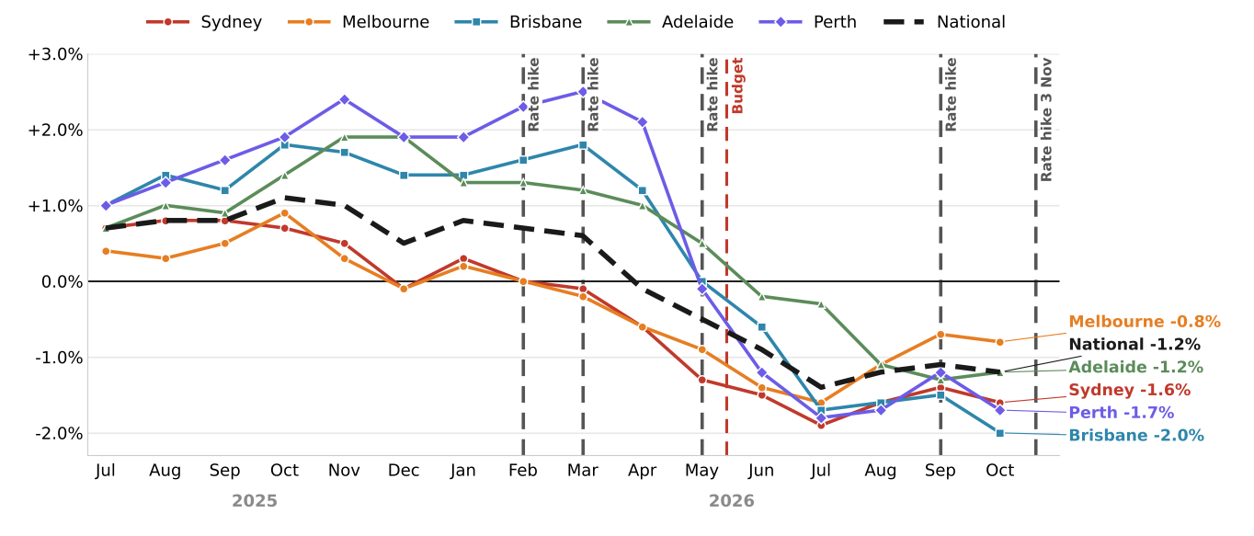
Interest rates are a blunt instrument designed to suppress demand. Yet housing (rents, new homes, council rates and electricity) is the single biggest driver of inflation, and higher rates do little to fix a supply shortage. In effect, the RBA is fighting a structural shortage with a demand tool. Government spending that grows faster than the economy can, across every level of government, only adds to the pressure.
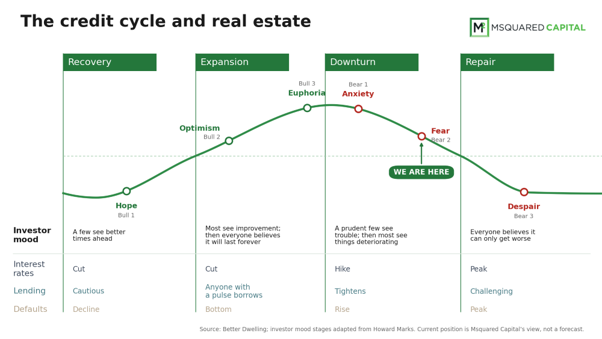
On credit, this is not a GFC-style freeze. It is a slow credit crunch. Borrowing from Howard Marks’ view that markets are driven by behaviour as much as economics, I believe the broader market is sitting in anxiety, while private credit is roughly halfway through the fear phase after several high-profile collapses.
That is where the opportunity lies. In lending, the deals to worry about are the ones written last year, not today. Debt pricing has reset, margins are wider, and borrowers are noticeably more cautious than a year ago. More short-term lending that banks would traditionally provide is now coming to private credit.
The best investors don’t act on emotion. They hold some liquidity because no one can pick the bottom, but they make sure they are in the market when it turns. Sitting on cash alone is not a strategy.